NEWS
Experian Activate Pre-Checks Loan Offers Before You Apply
Experian Activate pre-filters Marketplace credit offers with cash-flow data and lender rules, so shoppers see products they are likelier to get.

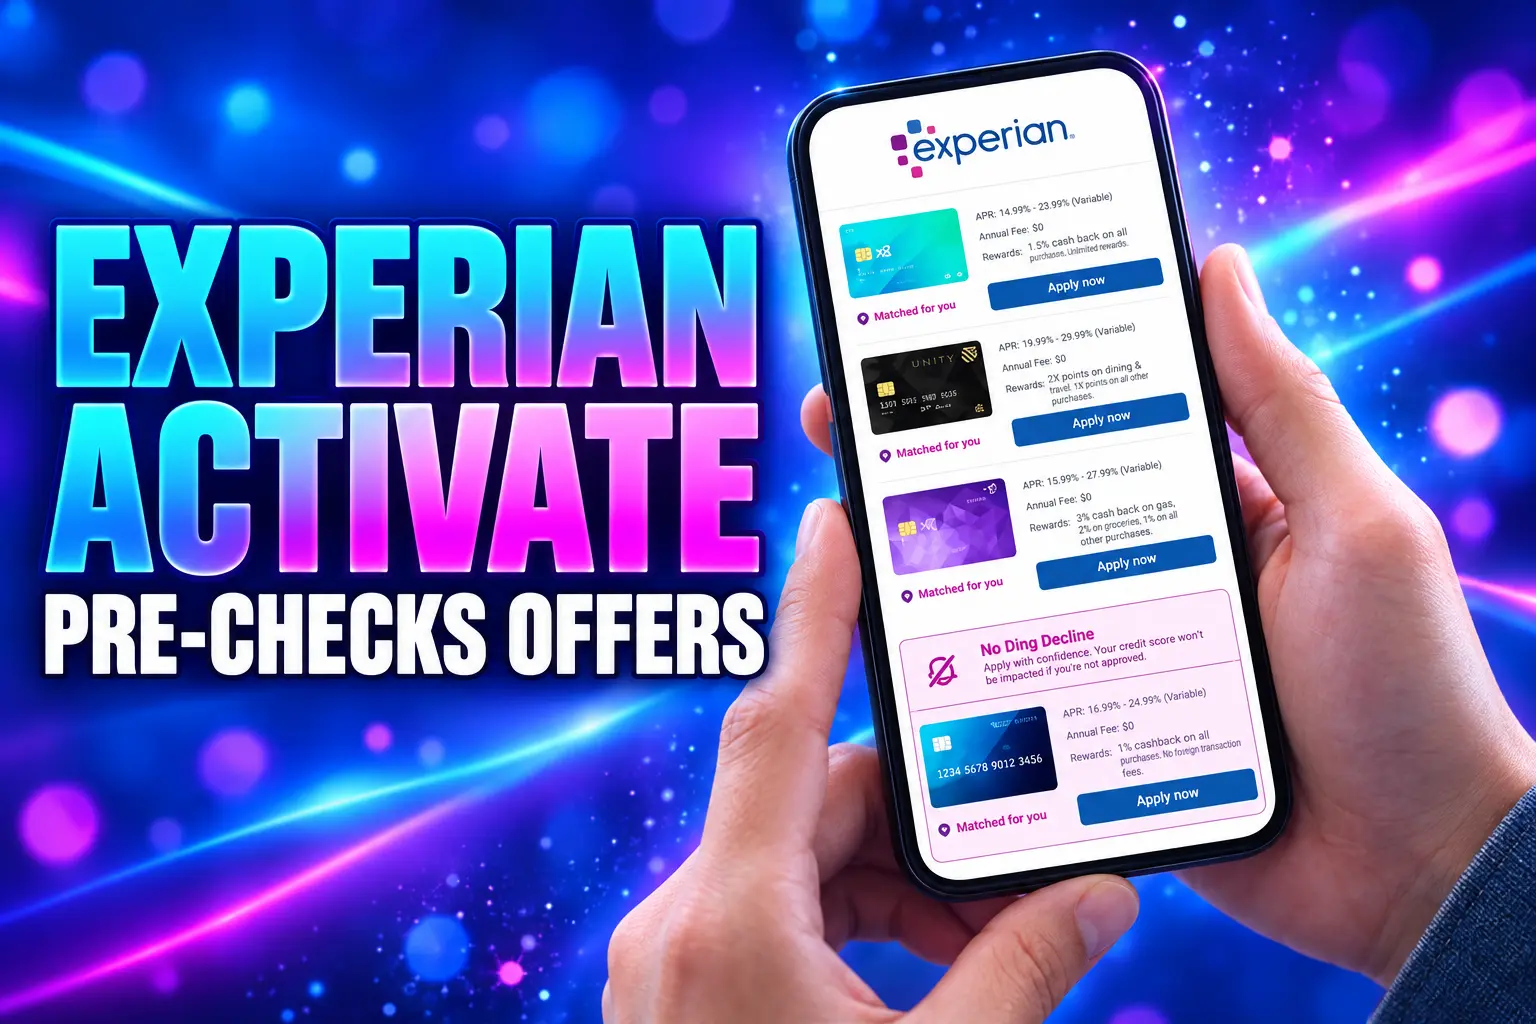
Experian rolled out Experian Activate on September 10, 2026, an AI engine that matches more than 90 million members to offers they are likelier to get. The engine runs on Experian Marketplace, the company’s comparison shop for credit cards, personal loans and auto insurance, and it scores shoppers against live lender rules plus permissioned cash-flow data.
The change is not a new row of ads. It is a filter. Offers that fail the match can disappear before a consumer taps apply, and Experian says the same real-time credit intelligence already feeds third-party surfaces such as ChatGPT.
Activate Turns Shopping Into a Pre-Check
Costa Mesa-based Experian described Activate as an AI-enabled decisioning engine that brings real-time lender defined underwriting criteria into the Marketplace. In the September 10 release, the company called it the only platform that puts credit files, analytics, AI, consumer-permissioned cash-flow insights and each lender’s own rules in one place. That claim is Experian’s. What the product does is simpler. It scores a shopper against those inputs while they are still browsing, then shows the offers that clear.
WHAT ACTIVATE COMBINES
- Credit files: The bureau snapshot of how a person has handled loans and cards over time.
- Analytics and AI: Models that rank which products fit the file and the lender’s rules.
- Permissioned cash flow: Bank-account income, spending and balances the consumer chooses to share.
- Lender rules: Each issuer’s live underwriting cutoffs, not a generic score band.
- Marketplace reach: The same member base Experian already uses to shop cards, loans and auto insurance.
Rakesh Patel, executive vice president of Experian Marketplace, said Activate “brings together the full power of Experian’s data, analytics, marketplace reach and AI capabilities to create a more intelligent lending experience.” The company also said consumers get relevant recommendations across platforms, and lenders can reach qualified borrowers wherever they are searching. Experian is a FTSE 100 data firm with 25,200 people across 33 countries and headquarters in Dublin.
The official account posted the launch the same day, framing cash flow as the extra signal next to the credit file.
Experian Activate™ is here. 🎉 Experian Activate brings real-time underwriting and cash flow intelligence to Experian Marketplace.
By combining credit data with real-time cash flow insights, Experian helps lenders make more informed decisions and expands access to financial… pic.twitter.com/lOBt0nTvj5
— Experian (@Experian) September 10, 2026
The Bank Link Happens in the Same Session
Ashley Knight, senior vice president of product management for financial services and data, wrote that cash-flow value does not start at the underwriting desk. It starts earlier, when a person is still picking a product. For members who connect a bank account, participating lenders can fold Experian Cashflow Attributes into the same session as the credit file. The September 10 release said that single connection also feeds Experian Boost, which lets people add bill-payment history to their Experian credit file.
By bringing consumer permissioned cash flow insights directly into the Experian Marketplace experience, we’re helping lenders extend more competitive offers to more consumers while creating a more seamless experience for people shopping for financial products that best meet their needs.
Ashley Knight, Senior Vice President of Product Management, Financial Services and Data, Experian, September 10, 2026 release
Knight’s separate product note put a number on the credit-side claim. Consumer-permissioned cash flow can help businesses approve up to 30% more applicants on average, she wrote, without changing their risk tolerance. That is an Experian figure, not a regulator’s audit, and it describes cash-flow insights in lending generally rather than a measured result from the Marketplace rollout. A June 5, 2025 collaboration with Plaid had already packaged the same idea as a Cashflow Score for lenders, built from permissioned transactions.
The practical sequence is the point. A shopper who links a bank account is not waiting for a second review after a decline letter. The extra data can change which offers appear while they are still on the page. People who skip the bank link stay on the credit file alone, and the match is thinner.
ChatGPT Already Carries Experian’s Offer List
Activate did not arrive in a vacuum. Experian spent 2026 putting Marketplace categories inside ChatGPT, then said the same real-time credit intelligence that powers the Marketplace also powers those third-party experiences. The chat surface is still a browse-and-handoff flow. Personalized matching, including pre-approved cards, happens after the user continues to Experian.
THE CHATGPT MARKETPLACE ROLL-IN
- February 12, 2026: Launches the Insurance Marketplace app on ChatGPT, letting users compare estimated auto rates from more than 37 carriers. Dacy Yee, president of Experian Consumer Services, said people could potentially save more than $1,000 a year on auto coverage.
- June 4, 2026: Opens the Experian Loans ChatGPT app, so users can explore personal-loan offers from lending partners inside the chat, then move to Experian for pre-qualified rates.
- August 20, 2026: Gives U.K. users authenticated access to a personalised 1250 Experian Credit Score inside ChatGPT. Experian said it powers 8 in 10 U.K. credit-card applications, and that 62% of regular ChatGPT users already turn to AI for financial goals.
- August 27, 2026: Adds the Experian Credit Cards app, moving the credit card marketplace into ChatGPT with annual fees, bonuses, rewards rates and APR ranges from the partner network.
Debbie Hsu, executive vice president of product for Experian Consumer Services, said consumers expect financial tools to feel as simple as the apps they already use. Michael Coleman, chief marketing officer at Credit One Bank, a named partner on the cards app, said the chat gives people a way to compare options “before they apply.” Future work, Experian said, includes more personalized card experiences and a wider lender panel.
The shortlist inside the chat is not the whole card market. It is the partner network Experian chooses to display, with offer fields the company manages so the assistant is not scraping random issuer pages. A shopper who wants a card from a bank that never joined the panel will not find it in that conversation. They have to leave.
Thin-File Shoppers Get a Second Look
Knight’s inclusion pitch is aimed at people whose bureau file is thin, stale or ugly relative to the money moving through their checking account. Experian commissioned Atomik Research to survey 2,000 U.S. adults from July 16 to July 21, 2026, with a margin of error of plus or minus 2.2 percentage points at 95 percent confidence. Among those who had been denied credit or given worse terms than they expected, 60% said the outcome would have been different if lenders had weighed recent income and banking activity next to the credit history.
THE CREDIT ACCESS MATH
- Marketplace members: More than 90 million people, per the September 10 release, up from more than 80 million in a May 11, 2026 Pagaya partnership note.
- Unscoreable adults: Federal Reserve staff calculations published in October 2025 estimate that 32 million American adults are unscoreable, including 7 million with no credit history (2.7%) and 25 million with a thin file (9.8%), against 258.3 million U.S. adults.
- Denied shoppers: 60% in the Atomik survey said extra income and bank data would have changed a prior denial or worse-than-expected terms.
- Approval claim: Cash-flow insights can help businesses approve up to 30% more applicants on average without changing risk tolerance, Knight wrote.
The Fed paper treats deposit-account cash flow as the alternative data with the cleanest tie to ability to repay, and it is cautious about models that have not been through a full downturn. Experian’s own business pages have been selling cashflow data to reach thin-file consumers for a while. Activate is the consumer-facing place where that pitch meets a live offer wall. People who never connect a bank still look like their bureau file. People who do connect give lenders a current picture, and they also give Experian another reason to be in the middle of the click.
Partner Lenders Reach the Shopper First
Activate is new as a branded Marketplace engine, and it is not new as plumbing. On May 11, 2026, Pagaya Technologies said it was embedding its lending models in Experian Marketplace and placing Pagaya’s model within Experian Activate, which that release called a hosted model environment. Pagaya, which said its network draws on more than $1 trillion in annual loan applications, was already using Activate to push real-time personal-loan recommendations to more than 80 million Experian members. Sanjiv Das, Pagaya’s co-founder and president, said the tie-up helps lenders connect with more qualified borrowers.
That history matters for who wins the shopper’s attention. A lender that loads its cutoffs, and optionally a third-party model, into Activate can bid on people who already look like a pass. A lender that stays off the panel does not get that pre-check, and its product does not show up in the filtered list, including in the ChatGPT apps that hand users back to Experian.
WHO SEES WHAT AFTER THE MATCH
| Party | What they put in | What they get back |
|---|---|---|
| Experian members | A credit file, and an optional bank link | Offers they are likelier to qualify for |
| Lenders on Activate | Live underwriting rules, and optional hosted models | Shoppers already scored against those rules |
| Lenders off the panel | Nothing | No place in the filtered list or the chat shortlist |
| ChatGPT users | A prompt and light comparison inputs | Partner-network terms, then a handoff to Experian |
The consumer benefit Experian advertises is fewer dead-end applications. The trade is a narrower shelf. Comparison shopping used to mean seeing products you might not get, then finding out the hard way. Activate is built to hide the miss. That is gentler on a credit file if it stops a doomed hard pull. It is also a quiet shift in who decides what counts as a relevant offer: Experian, the lenders who feed it, and the models those lenders park in the hosted environment.
Only 17 Percent Trust AI With Money
Experian is pushing credit shopping into chat at the same time its own research says most people do not want AI making money decisions. The 11th annual Identity and Fraud Report, released August 19, 2026, found that 31% of consumers have already used AI tools to shop and transact online, and another 23% would consider it. Comfort then falls. Only 21% said they were comfortable relying on AI for travel purchases. Only 17% said the same for financial services decisions.
That gap is the constraint on Activate’s ChatGPT path. A filtered offer list is useful if the shopper trusts the filter. It is a black box if they do not know which lenders were left out, which cash-flow attributes moved the rank, or whether a better card exists outside the partner network. Experian’s cards app tries to solve accuracy by feeding issuer-aligned fields into the chat, then sending the user to experian.com for profile-matched offers. Transparency still depends on the user noticing that the conversation was never a full market scan.
The August 27 cards release already flagged more personalized ChatGPT experiences and a larger lender panel. Activate is the scoring layer those extra lenders would use before an offer appears. For now, the engine is live on Marketplace, cash-flow is optional, approvals are not guaranteed, and the chat remains a doorway rather than a decision. The shopper who wants the product that never joined the panel still has to go look for it.
Frequently Asked Questions
Does Experian Activate Mean You Are Pre-Approved?
No. Experian’s own Marketplace footnotes say offers and approvals are not guaranteed, eligibility rules apply, and an application is subject to a credit check that may affect scores. On the cards path, “pre-approved” means the consumer met certain credit criteria set by the lender; identity, employment and income checks can still sink the file, and final approval itself triggers a credit check.
What Is the Experian Cashflow Score?
It is a separate 300 to 850 score Experian built with Plaid, announced June 5, 2025, from permissioned bank transactions rather than the Marketplace browse list. Experian said the score can deliver up to a 25% lift in predictive performance versus scores that use only conventional credit data, a different claim from Knight’s up to 30% more approvals figure. Plaid said its network reaches 1 in 2 U.S. bank-account holders and more than 12,000 institutions.
Will a Marketplace Application Hurt Your Credit Score?
It can. Experian’s card footnotes say applications use the FICO Score 8 model, and a lender may still use a different FICO version or another score entirely. Cards labeled No Ding Decline will not hurt scores if the consumer is not initially approved; if the application is initially approved, a hard inquiry still posts even when later verifications fail.
Which Products Sit on Experian Marketplace?
The September 10 Activate release names three consumer lines: credit cards, personal loans and auto insurance. Mortgage shopping is a separate build. Experian agreed in February 2026 to buy Own Up, an AI mortgage-shopping platform with a network of more than 40 lenders, to add home loans to the same Marketplace family.

America Exports Spare Diesel as Pump Prices Hit Records

Eto’o Pushes Infantino’s Re-Election as FIFA Ignores His Qatar Fees

Kalshi Asks 11 Judges to Undo a Sports-Swap Split

Experian Activate Pre-Checks Loan Offers Before You Apply

Nvidia’s 2 GW Australia Bet Runs Through the Grid

Long Realty Drops Lundeen After the Flight 618 Arrest

Land Rover Pushes the Electric Defender Into the 2030s

Boox Picco Drops Phone Magnets for a Pocket Linux Reader

OPEC+ Holds October Oil Output After Six Paper Hikes

Domino’s Paid Customers to Test an App Already Live
-
 BUSINESS3 weeks ago
Long Realty Drops Lundeen After the Flight 618 Arrest
-
 AUTO4 weeks ago
Land Rover Pushes the Electric Defender Into the 2030s
-
 NEWS3 weeks ago
Boox Picco Drops Phone Magnets for a Pocket Linux Reader
-
 BUSINESS3 weeks ago
OPEC+ Holds October Oil Output After Six Paper Hikes
-

 TECHNOLOGY3 years ago
Why Was My Amazon Order Cancelled – Understanding Order Cancellation Reasons
-
 LIFESTYLE3 years ago
How to Get Signed by Atlantic Records – Pursuing Record Deals with Major Labels
-
 NEWS3 weeks ago
Domino’s Paid Customers to Test an App Already Live
-
 LIFESTYLE3 years ago
American Eagle Style Number on Tag – Decoding Clothing Label Information